DRAM Module Revenue Surges 59% YoY in 2025 as Crowding-Out Effect Constrains Chip Supply and Drives Prices Higher, Says TrendForce
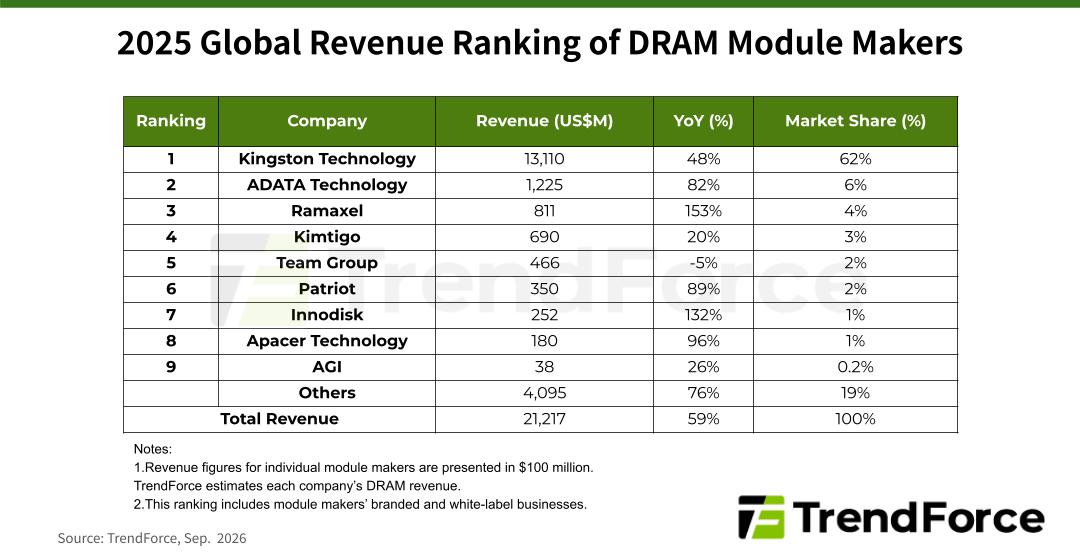
According to TrendForce statistics, the global DRAM module market generated $21.2 billion in revenue in 2025, up a strong 59% YoY. Rising prices and concentrated shipments from DRAM module makers in the second half of the year helped drive growth. This marked a significant acceleration from the 7% growth recorded in 2024.
DRAM market conditions changed dramatically between the first and second halves of 2025. In early 2025, some module makers increased their inventories of DDR4 chips in Q2, spurred by tariffs and the end-of-life (EOL) plans of DRAM suppliers for DDR4. They also supplied PC OEMs and other consumer electronics customers that had pulled forward procurement in response to tariffs.
In the latter half of 2025, North American and Chinese CSPs increased server DRAM orders to support the computing needs of agentic AI applications. This demand surge limited DRAM suppliers’ allocations for PC and consumer applications, leading to higher overall DRAM prices. As shipment volumes and prices for modules increased, most module makers experienced a market upswing, with many reporting significantly higher revenues in the second half compared to the first.
Revenue growth varied among module makers depending on their target markets and business strategies. Overall, given the long-term growth potential of customer demand and customers’ ability to absorb memory price fluctuations, module makers have become more aggressive in expanding into industrial and enterprise server product lines. They also adjusted their product portfolios in response to the generational transition, making DDR5 their primary product line in the second half of the year.
The top five global DRAM module makers accounted for 77% of total market revenue in 2025, while the top nine represented 81%. Market leader Kingston maintained a dominant 62% share. Leveraging its industry-leading procurement scale, the company built ample inventory throughout 2024 and 2025, positioning it to aggressively supply the channel market as prices strengthened in the second half of 2025. This strategy helped drive full-year revenue growth of 48% YoY.
ADATA ranked second, with DRAM revenue rising 82% YoY in 2025. The company’s low-cost inventory—accumulated during the previous market cycle—became a key contributor to stronger profitability as upstream supply tightened and module prices increased in the second half. ADATA also continued to secure relatively stable chip supply allocations through partnerships with DRAM suppliers. Going forward, its strategy will focus on expanding its low- and mid-capacity RDIMM business.
Third-ranked Ramaxel focuses primarily on strategic partnerships with PC OEMs and CSPs. Its revenue surged 153% YoY in 2025, the highest growth rate among the companies in the ranking. Building on its PC module business, Ramaxel further expanded strategic RDIMM partnerships with domestic DRAM suppliers and CSPs, playing a key role in scaling up and improving the quality of China’s domestic RDIMM supply chain.
Kimtigo ranked fourth, with revenue increasing 20% YoY in 2025. The company has an established presence in China’s domestic market, with a product portfolio spanning consumer, industrial, and enterprise applications. As DRAM supply gradually tightened in the second half, Kimtigo also stepped up its efforts to expand its OEM customer base.
Team Group ranked fifth in 2025. The company supplied DDR5 products to the North American channel market as DRAM prices rose rapidly in the second half.
Patriot Memory ranked sixth, with revenue surging 89% YoY in 2025. Its diversified presence across consumer, gaming, industrial, and edge computing applications allowed it to capitalize on the DRAM supply shortage in the second half. Innodisk, which focuses on the industrial market, took seventh place, with revenue soaring 132% YoY. In addition to higher prices, growing momentum from edge AI projects provided an increasingly significant contribution to its growth.
Apacer ranked eighth, with DRAM revenue rising 96% YoY in 2025. With a strong focus on the industrial market, the company began securing additional supply in the second quarter to meet customer demand amid DDR4 EOL and the worsening supply-demand imbalance in the second half. This strategy also enabled Apacer to translate rising DRAM prices into stronger operating results.
Finally, AGI placed ninth, with DRAM revenue increasing 26% YoY in 2025. The company primarily serves the consumer retail market under its own brand and uses cross-border e-commerce as its main channel for overseas expansion, with sales spanning Japan, Europe, and the U.S.

The memory market watcher
DRAMeXchange is a global primary provider of future intelligences, in-depth analysis reports and advisory services on DRAM and Flash memory industry with coverage including current business, spot trading prices, and market trends, capital spending and wafer capacity trends, the impact of DRAM/flash memory products on the market, and other relevant PC industry information.
© DRAMeXchange ® Tech.Inc. All rights reserved.